CBAM / Vietnam
Your EU Customer Needs Carbon Evidence. Can Your Vietnamese Supply Chain Deliver It?
What SGS’s CBAM services signal for smaller manufacturers: the next export bottleneck may not be your production capacity, but the evidence behind the metal you buy
By Dr. Elvis Mujagić · October 17, 2026 · 10 min read
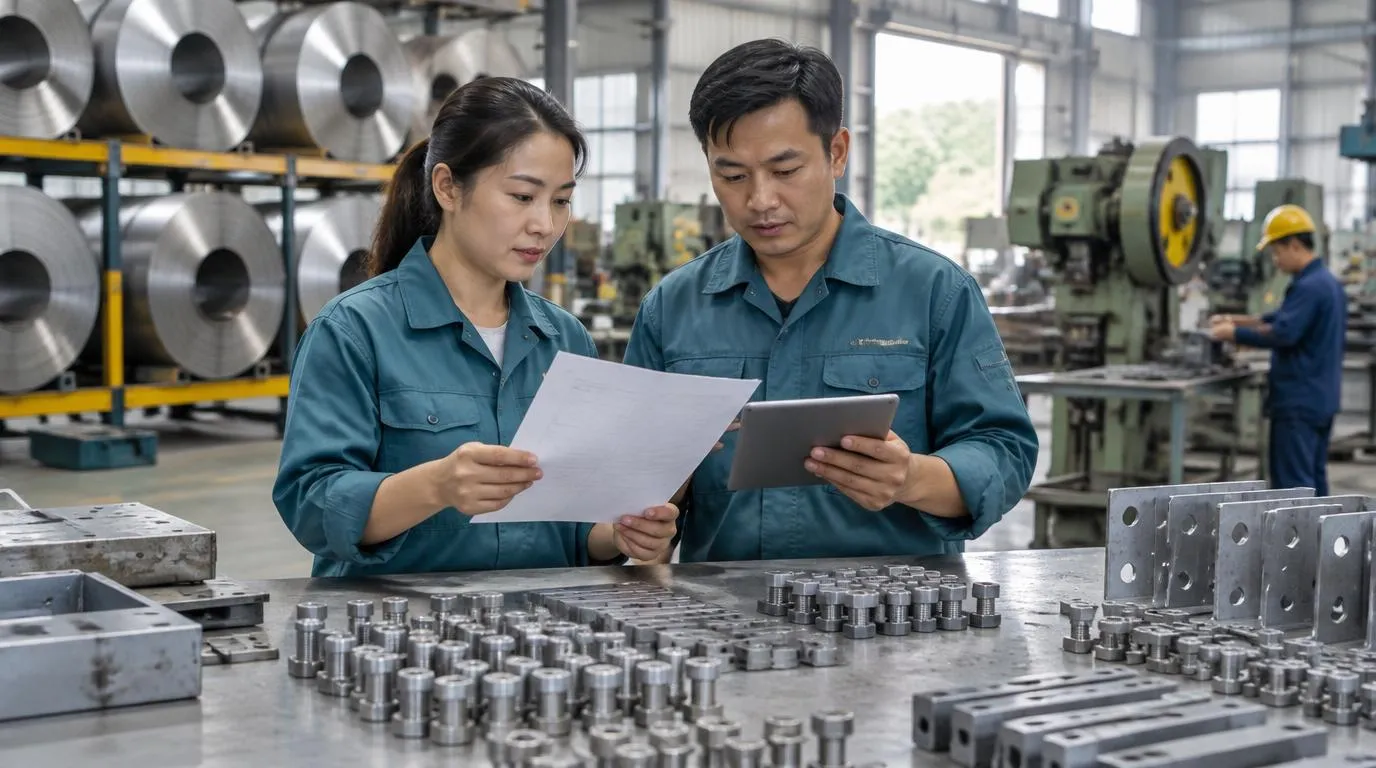
Your customer in Europe asks for the emissions behind a shipment of metal parts. Your team knows the weight, the grade, the delivery date and the price. What it cannot immediately produce is a defensible link between those parts, the steelmaking installation and the emissions of the material used. The goods are ready. The evidence is not. For a smaller Vietnamese manufacturer, that can turn a routine order into a difficult commercial conversation.
Our first Vietnam article asked whether the country’s carbon market would reduce an exporter’s CBAM exposure. The second looked at what Hoa Phat’s green steel direction means for competitors. This third article moves onto the factory floor: how does a manufacturer that buys its steel or aluminum from someone else assemble evidence its customer can actually use?
SGS’s public CBAM service material provides the starting point. Its focus on emissions calculations, reporting support and verification reflects a real need in the market. Our analysis is independent: this is not an endorsement, a claim of partnership or a statement that every SGS service is compulsory. The business question is what must work inside your company before outside expertise can help.
First, separate a legal obligation from a customer request
“We make metal products” is not a CBAM classification. The legal test starts with the Combined Nomenclature, or CN, code of the goods imported into the EU and the scope in Annex I of the CBAM Regulation. Certain iron and steel articles, including specified fasteners and structures, are already covered. A different finished component may sit outside the current list. Its use of steel does not, by itself, put it inside CBAM.
That distinction matters for spring makers, precision workshops, fabricators and suppliers to machinery manufacturers. Check the actual code and product description rather than assuming that every downstream article is covered, or that every smaller manufacturer is exempt. Proposals to extend downstream coverage must also be distinguished from rules already in force.
A second question is whether the customer wants information for its legal CBAM declaration, for a product carbon footprint, or for a broader purchasing requirement. Those are not interchangeable calculations. An EU buyer can request carbon evidence for an out-of-scope product under its own procurement policy. That is a commercial request, not proof that your shipment attracts CBAM certificates.
The amended EU rules introduce a 50-tonne annual mass exemption for the relevant covered goods, with different treatment for electricity and hydrogen. This is assessed at the importer level, not separately for each Vietnamese supplier or each delivery. A small shipment to a large importer is not automatically exempt. Ask your buyer how your goods fit its annual position before building your response around a threshold.
Do not spend money answering the wrong question. Establish what the product is, what the buyer needs and which calculation applies.
Why your own factory data may not be enough
Consider a workshop that buys wire rod, forms it into covered fasteners and sells to an EU importer. It may have good records for its own production: fuel consumption, output, scrap and material purchases. But the rod arrived with emissions from earlier production. Where the CBAM methodology requires those relevant precursor emissions, recording only the workshop’s own activity leaves a gap.
The gap grows when material comes through a trader. The invoice identifies the seller. It does not necessarily identify the installation that made the metal, the production route, the applicable reporting period or the emissions value linked to that material. A mill certificate may establish grade and technical properties without establishing a CBAM-compatible emissions figure.
This is why a generic “low-carbon steel” brochure is not an evidence pack. Neither is a company-wide sustainability report. Both can provide useful background, but neither automatically supplies the product and installation information required for your customer’s calculation. Your purchasing department needs to ask for the missing evidence, not simply forward whichever environmental document is available.
For covered iron, steel and aluminum goods, the definitive CBAM framework currently focuses on direct emissions under Annex II. Other sectors have different treatment. Collecting electricity records may still be useful for wider customer requirements and your own management, but do not add every electricity-related footprint to a CBAM figure without checking the applicable method. More data is not the same as the right calculation.
What the SGS service offering tells you, and what it does not
SGS presents CBAM support across areas such as understanding requirements, preparing emissions information and verification. The important signal is not that a manufacturer should outsource everything. It is that a calculation, a report and independent verification are separate pieces of work. A spreadsheet can be complete in appearance and still lack the supporting evidence an independent verifier needs.
The EU importer remains responsible for its CBAM obligations. The producer supplies the installation and production information needed where actual emissions are used. An independent verifier with CBAM accreditation from an EU national accreditation body checks the information within its accredited scope. An advisor can help organize preparation. None of these roles removes the need for accurate source records inside the factory. Confirm the specific verification entity and accreditation, not just its group brand.
Also distinguish a greenhouse gas inventory verified to ISO 14064-1 from verification of embedded emissions under CBAM. An organizational inventory can be a valuable foundation, but it is not automatically a CBAM verification report for a specific product and production process. Before commissioning work, confirm the methodology, accreditation scope, installation coverage and deliverable the EU customer needs.
Preparation and independent verification must remain properly separated. Ask a service provider how it protects impartiality if its group offers both advisory and verification services. A provider’s brand name alone does not establish that the proposed engagement satisfies the relevant independence and accreditation requirements.
A smaller manufacturer’s problem, in practical terms
Take an illustrative Vietnamese fastener manufacturer, not an actual client. It buys wire rod from two traders, changes sources when prices move and combines material in stock. Its EU customer requests actual embedded emissions for covered goods. Sales sends the request to quality. Quality asks purchasing. Purchasing asks the traders. One sends a sustainability brochure; the other sends an emissions value without a clear installation or reporting period.
The problem is not a missing software subscription. It is a broken information chain. The company cannot reliably connect the claimed emissions value to the inputs used in the relevant production. Even a competent outside advisor cannot manufacture evidence that the supplier has not provided.
A workable response starts with one product family and its relevant material inputs. Identify the actual producing installations, obtain the applicable emissions information, document the allocation method and flag unresolved gaps. If actual data cannot be supported, discuss the permitted default-value approach and its implications with the importer. Do not replace missing data with a favorable estimate and label it verified.
Build an evidence pack, not a folder of unrelated PDFs
- 1.
Agree the question with your customer
Record the CN codes, covered goods, importer contact, reporting period and required method. Confirm whether the request is for CBAM, a product footprint or a purchasing questionnaire. Get the required format and deadline in writing.
- 2.
Identify the producer behind the seller
For relevant precursors, map the trader to the actual producing installation. Ask for the installation identity, production route and applicable emissions information, with supporting documentation. Track unanswered requests instead of treating an email sent as a task completed.
- 3.
Connect purchased material to your production
Keep purchase, receipt, stock, output and scrap records that support the required material balance and allocation. The exact method depends on the process; the goal is a defensible calculation, not a promise that every part can be traced to one individual heat.
- 4.
Check the numbers before sharing them
Confirm units, periods, system boundaries and whether figures are actual or default values. Reconcile totals and retain calculation versions. A value in tonnes of CO2 equivalent per tonne is not the same as a company’s total annual emissions.
- 5.
Prepare for independent checking
Confirm the verifier’s relevant accreditation and scope, the records it will need and any applicable site-visit requirements. Resolve missing precursor evidence before the engagement, rather than expecting verification to repair the data collection.
- 6.
Give the buyer one controlled response
Nominate one internal owner to send the approved information and record questions or corrections. Protect supplier confidentiality through agreed access arrangements. Preserve the audit trail when data changes; do not silently overwrite a file the customer has already used.
Put data availability into your purchasing decision
A supplier’s quote tells you the material price. It does not tell you the administrative effort, uncertainty or possible CBAM cost associated with missing evidence. Two offers for the same grade can therefore create very different outcomes for an EU order. Purchasing should assess the ability to provide usable emissions information alongside price, quality and delivery reliability.
That does not justify switching suppliers on an untested assumption. Compare the actual alternatives with the importer: supported actual emissions, permitted defaults, applicable adjustments and the terms under which costs are shared. Verified actual data does not guarantee a lower certificate cost. A high-emission installation can produce an unfavorable actual figure. The value is knowing the position rather than promising savings you cannot substantiate.
Build evidence requirements into purchase agreements and supplier onboarding. Define the information requested, the update frequency, responsibility for changes and a process for missing data. For a small workshop, a clear request and a disciplined register can be more useful than a complex system nobody owns. Add tools when the workflow is understood, not as a substitute for it.
Start with the order you need to protect
Our view at wis.dom|bridge is straightforward: start with the business exposure, then organize the evidence. Which EU customer matters most? Which product is actually covered? Which supplier holds the missing information? Who inside your company has the authority to get it? Answering those questions is more useful than launching a company-wide carbon project without a defined purpose.
Vietnam’s carbon-market development is one part of the story. Hoa Phat’s investment direction is another. For the smaller manufacturer, the immediate task is closer to home: make sure the metal entering your factory comes with information that can follow it into a customer’s calculation. You cannot control the whole European regulatory system. You can control whether your own response is organized, honest and usable.
Find the gaps before your EU buyer does
Our free CBAM Readiness Assessment is a starting point for understanding product exposure, supplier-data gaps and the work to prioritize. It does not replace a formal customs classification or independent emissions verification. Use it to prepare a focused discussion with our CBAM team.
Start the free CBAM assessmentSources and editorial references
- SGS Vietnam, “CBAM Compliance”, undated service page, accessed October 17, 2026 (sgs.com). Service descriptions are the provider’s own statements, not legal requirements.
- SGS, “Navigating Carbon Border Adjustment Mechanism Pre-Verification: Key Requirements for Compliance”, November 20, 2024 (sgs.com). This preparation guidance predates the definitive-regime updates.
- Regulation (EU) 2023/956 establishing CBAM, May 10, 2023, particularly Annexes I, II and IV and the provisions on verification (EUR-Lex: eur-lex.europa.eu).
- Regulation (EU) 2025/2083 simplifying and strengthening CBAM, October 8, 2025, including the annual mass threshold (EUR-Lex: eur-lex.europa.eu).
- European Commission, Carbon Border Adjustment Mechanism portal and guidance for non-EU installation operators, accessed October 17, 2026 (taxation-customs.ec.europa.eu).
- European Commission, CBAM Verification, including Regulations (EU) 2025/2546 and 2025/2551 and August 2026 verification guidance, accessed October 17, 2026 (taxation-customs.ec.europa.eu).
This article is our own analysis of the sources listed. Third-party rights remain with their owners. The workshop example is hypothetical, not a reported client outcome. Scope and methodology must be checked for the specific product, installation and import situation; this article is not legal advice or a verification opinion.
Dr. Elvis Mujagić
Dr. Elvis Mujagić is Partner and Head of CBAM at wis.dom|bridge™. He advises companies on CBAM cost exposure, implementation and the link between carbon data, sourcing and financial planning.